Growth with Protection
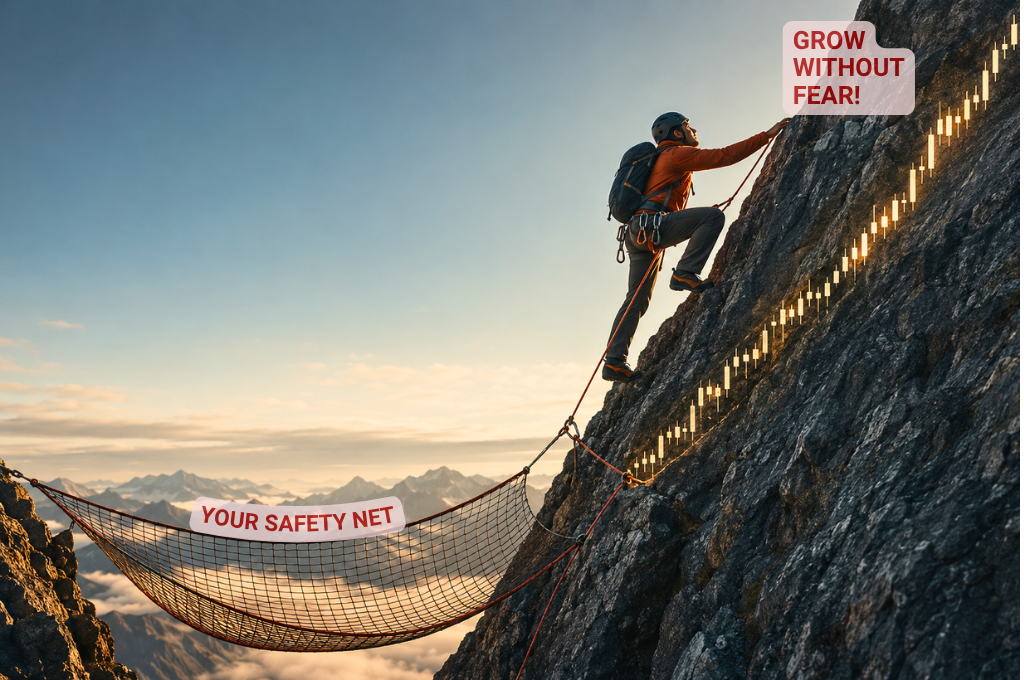
Large drawdowns can damage the compounding journey.
“Can we participate in equity growth while making the portfolio more resilient to major market falls?”
ILTS is built around that question. It does not attempt to eliminate market risk or promise a fixed return. It combines equity/index participation with a systematic put-option hedging framework.
Ideas behind the strategy.
- GROW Equity participation
- PROTECT Put-option hedge
- REDEPLOY Opportunity after falls
- COMPOUND Long-term recovery
1
Index exposure
2
Systematic hedging
3
Redeployment
Protection → Payoff → Lower levels → More units → Recovery participation → Compounding
ILTS should be evaluated over a market cycle —not one good or bad year.
When markets rise
When markets are volatile
When markets fall sharply
The insurance analogy: Protection can feel like a cost when nothing goes wrong. Its value becomes visible when the event it was designed for actually occurs.
What should an investor realistically expect?
| Horizon | What to understand |
|---|---|
| Short term | Equity/index participation continues, but the investor bears the economic cost of protection and implementation. |
|
Medium term |
A meaningful correction can potentially create value from the hedge and may compensate for some or all of accumulated protection cost, depending on timing and magnitude. |
| Long term | Across multiple market cycles, the objective is a more resilient drawdown profile and the potential benefit of redeployment after major falls. |
We are not trying to eliminate the crash. We are trying to make the crash more manageable—and potentially more useful.
Not simply “between debt and equity.”
| Characteristic | Debt-oriented investment | Unhedged equity | ILTS |
|---|---|---|---|
| Primary objective | Income / capital stability | Capital growth | Equity growth with systematic protection |
| Upside potential | Generally limited | High | High |
| Downside mechanism | Depends on instrument, issuer and duration risks | No built-in hedge | Put-option hedging framework |
| Long-term driver | Yield / income | Equity earnings and valuation | Equity growth + protection/redeployment mechanism |
ILTS may be relevant for someone who says: “I want long-term equity growth, but I am uncomfortable with large drawdowns and value a systematic protection framework.”
Return is only half the conversation.
Return
Drawdown
Risk-adjusted outcome
For sophisticated investors: This is where measures such as maximum drawdown and Calmar ratio can provide additional perspective.
Tax can be a supporting benefit —not the reason to buy.
Equity / ETF component
Futures component
Professional advice
What ILTS cannot promise.
- No guaranteed capital protection or fixed capital floor.
- No guaranteed minimum, target or fixed annual return.
- No guarantee of outperforming the unhedged index.
- Protection can lose value because of time decay, rolling and market conditions.
- The hedge may not fully offset every market decline.
- Futures, leverage, margin, financing, basis, execution and transaction costs create additional risks.
- Tax and regulatory treatment may change.
- ILTS can underperform an unhedged index during sustained rising markets.
Suitability: ILTS is intended for investors with a long-term horizon who understand equity-market risk and are willing to accept that protection has an economic cost. It is not a substitute for a bank deposit or guaranteed-capital product.
ILTS may be worth exploring if…
✓ You want equity growth
✓ Drawdowns concern you
✓ You can be patient
You understand that protection has a cost and that the strategy should be evaluated over meaningful market cycles.
ILTS may not be appropriate if your primary requirement is guaranteed capital, predictable short-term income, or a fixed annual return.
We work for you, not for products
Finideas charges clients an agreed advisory fee. We do not receive commissions, referral fees or other monetary benefits from AMCs, PMS providers, brokers or other financial-service providers.
This helps create a transparent advisory relationship where the focus remains on your financial objectives, risk profile, liquidity needs and suitability.
24+ Years
Fee Only Advisor
For Unbiased Solution
35+ Advisors
AI Depth
ILTS may be worth exploring if…
Let's understand whether it fits your portfolio.
What happens next?
- Our team reviews your enquiry.
- We contact you for an initial discussion.
- We understand your investment objective and suitability.
- We explain ILTS, costs, risks and implementation in detail.